Key takeaways:
- HR leaders can protect employee affordability without shifting costs by focusing on three strategic levers: pharmacy management, health plan design, and AI-powered benefits education.
- Proactively managing high-cost GLP-1 drugs through clinical programs, Pharmacy Benefit Manager (PBM) audits, and HSA-eligible coverage options can meaningfully reduce pharmacy spend.
- Revisiting HDHP plan design, including offering stronger Health Savings Account (HSA) seed contributions, helps close the gap between high deductibles and what employees can realistically afford out of pocket.
If healthcare inflation had tracked like everything else since 1969, you’d pay about $14.57 for a pound of apples in 2025, roughly $5 to $7 for a single apple.1 That comparison feels extreme, but it mirrors what benefits teams face every day: real pressure to protect employees’ access to care while keeping total spend sustainable.
Employers are operating in a landscape defined by economic fluctuations and uncertainty. Experts predict a 6.5% rise in total benefit costs per employee in 2026 – the steepest rise in 15 years. Additionally, 59% of employers plan to cut costs this year.2
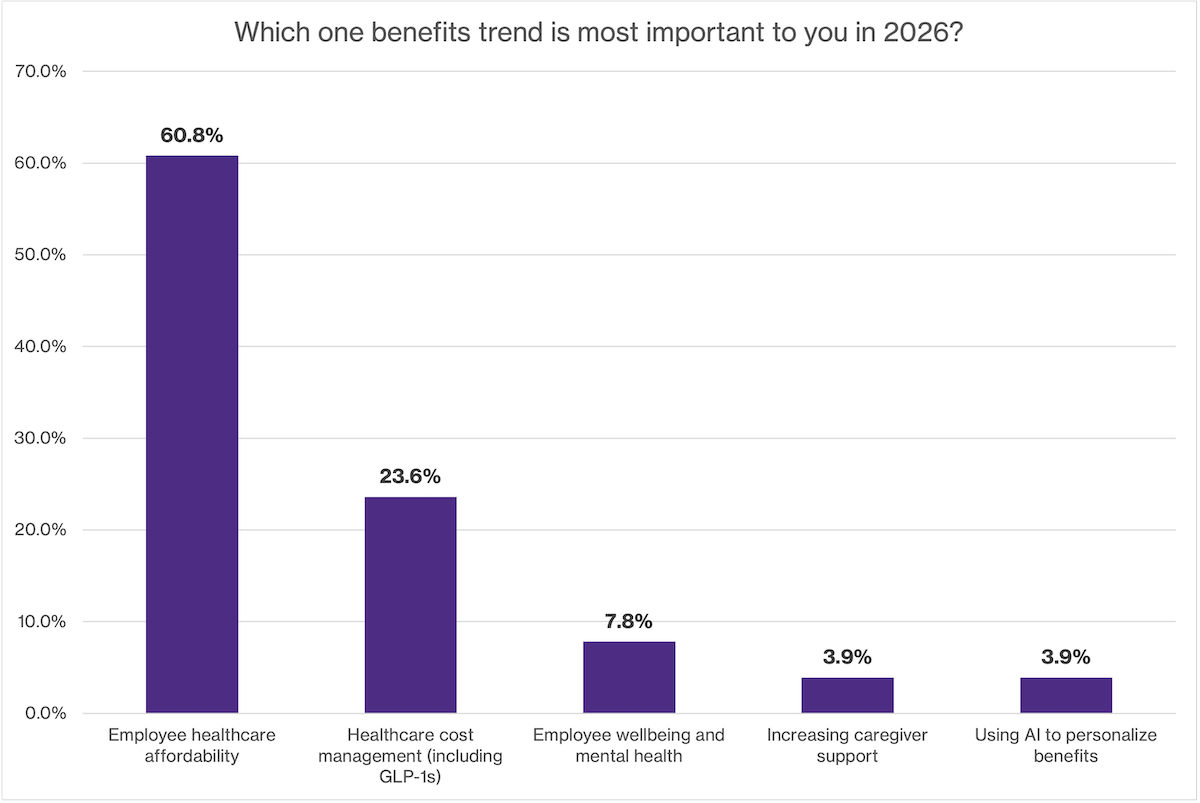
However, employers are unwilling to shift costs to employees. In a HealthEquity webinar, attendees told us employee healthcare affordability was the most important trend for 2026 (60.8%), clearly signaling that it’s a priority over cost management (23.5%).3
The challenge is clear: How do you balance the budget without compromising the care your employees need? Here are three strategic ways to address healthcare affordability in 2026.
How can employers manage rising GLP-1 costs?
For many employers, GLP-1s represent a dilemma. They offer significant health benefits for employees struggling with obesity and diabetes, but they come with a high price tag. According to a recent Mercer report, only 44% of employers are currently covering them for weight loss.4
GLP-1s can deliver meaningful health outcomes, but they can also drive outsized pharmacy trend, fast. Employers don’t need to choose between access and cost control. They can introduce guardrails that support appropriate use and create a clearer line of sight into what they’re paying and why.
Here are steps benefits leaders can take now:
-
Implement clinical programs: Employers, including Ned Godwin of TIAA, are implementing weight management programs as part of their GLP-1 strategy. Employees can enroll to meet with a dietitian, get personalized support, and monitor their prescription as part of their strategy. This ensures that the medication is part of a holistic health strategy rather than a standalone cost.
-
Review Pharmacy Benefit Manager (PBM) partnerships: Now is the time to audit PBM contracts. Are you getting the transparency you need? Do you have access to the data for better decision-making? Some employers are exploring alternative PBMs or point solutions that specialize in high-cost drug management to ensure they are not overpaying for their prescriptions.
-
Encourage HSA use for GLP-1 costs: Let employees know that they can pay for these drugs using their HSA dollars. HealthEquity partnered with Agile Telehealth5 to offer our HSA members access to weight management solutions that are payable using their pre-tax HSA savings. Members can pay for eligible care with tax-advantaged dollars through their HealthEquity account, helping their healthcare spending go further.
-
Review Pharmacy Benefit Manager (PBM) partnerships: Now is the time to audit PBM contracts. Are you getting the transparency you need? Do you have access to the data for better decision-making? Some employers are exploring alternative PBMs or point solutions that specialize in high-cost drug management to ensure they are not overpaying for their prescriptions.
How does health plan design improve healthcare affordability?
How often are you evaluating the design of your high-deductible health plan (HDHP)? Or looking at your contribution strategy for your HSA program?
According to the Kaiser Family Foundation, the average HDHP + HSA plan deductible is $3,650, while the average employer HSA contribution is just $960.6 This makes it difficult for employees and their families to choose the HSA option – they’ll have to come up with $1,590 every year to cover the difference, and that’s not easy with today’s economic headwinds.
Here’s what Michon Caton, Reward Partner at Roche / Genentech shared with us in a recent webinar:
We offer a pretty nice [HSA contribution] seed to our employees. Oftentimes, that’s what really helps our employees understand the benefits of even participating in an HSA. It helps them understand the seed that we’re giving you can be applied to your deductible, which reduces the employee’s dollar amount out of their pocket.
Seed contributions reduce the anxiety of starting with a high deductible on the first day of the plan year, even in combination with a match contribution.
HDHP and HSA plan design: implementation checklist
- Auto enrolling new hires in the HDHP + HSA plan.
- Automating payroll contributions equivalent to the premium savings compared to the PPO plan.
- Benefits education efforts to bust common HDHP and HSA myths.7
How can AI personalize the benefits experience?
When employees can’t quickly understand their options, they often default to higher-cost choices, like using the ER for non-emergencies or skipping preventive care because they expect a bill. AI can help reduce that friction by helping employees get answers in the moment they need them.
You can use AI in a practical, benefits-friendly way:
- Offer a benefits chatbot or AI search experience that pulls from your actual plan resources. Employees should be able to ask, “Is this covered?” or “How do I find in-network care?” and get a clear, consistent answer.
- Steer employees to cost-effective sites of care. Build prompts and pathways that help guide employees toward urgent care, telehealth, or primary care.
- Use time savings to focus on high-impact work. When AI handles routine questions, your team can spend more time analyzing plan performance, improving communications, and negotiating vendor terms.
Forward-thinking benefits leaders are using AI to help employees access the right info, understand their benefits, and make informed decisions.
We actually just released a new HR chatbot. It has actually done a scrape of our benefits portal. You can ask it almost any benefits question. Like any AI tool, it’s still learning, but the answers are very good. It gives great information on plan design, recommendations, on how to get in-network care, and things of that nature.
- Ned Godwin, VP of Benefits at TIAA
By automating routine inquiries and benefits education, your HR team can reclaim hours previously spent on administrative tasks. This allows you to focus on high-value strategic initiatives—like analyzing plan design effectiveness or negotiating better vendor rates—that directly impact your bottom line.
Turning uncertainty into opportunity
The landscape of healthcare will undoubtedly bring challenges. Whether it’s pharmacy benefit costs, plan design, or the rise of AI, benefits teams are tackling some of the fundamental trends that are impacting employee’s lives. But one thing is clear: employers care about supporting employees through rising costs.
Emily Roberts, VP, Director of Benefits at Fidelity National Financial, shared her perspective during our recent webinar:
I want everyone to be happy, but when we have to make major changes, the person I think about is that lower-income earner, and what impact that is going to have on them.
This is the heart of the challenge for benefits leaders. They are at the intersection of affordability for their employees AND for their organization. By actively managing high-cost drivers like GLP-1s, investing in employee’s healthcare savings, and leveraging technology to guide better decision-making, you can build a benefits program that may help address healthcare affordability for your people.
Frequently Asked Questions
References and disclosures
2 Disclaimer: Results may vary based on employer size, demographics, and plan design
3 Mercer, “Employers prepare for the highest health benefit cost increase in 15 years,” September 2025.
4 Mercer, Survey on health & benefit strategies for 2026.
5Agile Telehealth and HealthEquity are separate companies and are not responsible for each other's policies or services. When you engage with Agile Telehealth through a HealthEquity link, we may earn a referral commission.
6 KFF 2024 Employer Health Benefits Survey-Sections 7 and 8 HSA Plan composite Deductible and Employer Contribution @ 57% single-enrolled and 43% family-enrolled, numbers shown rounded to nearest 10.
7 Disclaimer: Actual savings and adoption rates may vary.
HealthEquity does not provide legal tax or medical advice.